Markets, Business & Tech Briefing: Montenegro Rings the New York Closing Bell on Tuesday, a Golegã Sauce Maker Eyes Morocco, a Portuguese Fintech Lands on Pix
📋 In This Edition
- The Week the PSI Set a Record and Gave It Back Twenty-Four Hours Later
- Portugal Carries 3.90 Percent Into Monday, and France Spent Saturday Explaining Why It Pays 4.57
- Friday's Euribor Landed This Morning, and the Two Fixings That Matter Went Opposite Ways
- Brent Settled at 103.87 Dollars, and Macron Wants a G7 on Opening the Strategic Reserves
- Montenegro Rings the New York Closing Bell on Tuesday, in a Year Portugal Sold the Americans 9.7 Billion Euros
- A Golegã Sauce Maker Buys Dona Sarah, and Has a Moroccan Factory on the Table
- Bleap Puts Brazil's Pix Inside a European IBAN, and Trade Republic Gives Its Old Clients Forty-Eight Hours
- Three More Deals: Fitness Park, an Aircraft Maintenance Firm, and Impresa's Programme Guides
- German Investors Are Watching Sines, and the Complaint Is the One You Would Guess
- Knight Frank Puts Comporta on Europe's Luxury Map, and a London Lawyer Builds Eleven Villas Above Faro
- Also: BCP's Buyback Passes 232 Million, AICEP Changes Hands on 1 October, and Açoreana Disappears After 134 Years
- Monday
Euronext Lisbon closed on Friday evening and does not reopen until Monday morning, so no Portuguese share changed hands today. Two things did move while the exchange was shut. Paris published a debt projection on a Saturday, which is not a thing finance ministries do when the news is good, and Friday's Euribor fixings were published here this morning, a day late as always. Everything else in this edition is corporate: an aircraft maintenance business, a gym chain, a sauce maker in the Ribatejo and a fintech that has quietly wired Brazil's instant payment system into a European bank account.
And on Tuesday, for the third time in modern Portuguese history, a Portuguese leader will stand on a balcony above the floor of the New York Stock Exchange and press the button that ends the session.
The Week the PSI Set a Record and Gave It Back Twenty-Four Hours Later
The PSI finished the week at 9,542.21 points. That is 17.48 points, or 0.18 percent, above the 9,524.73 at which it closed on Friday 11 September, so the five sessions netted out to almost nothing. The path between those two numbers was anything but flat.
Thursday's close of 9,671.11 was the highest the index has printed in a year, and it still sits at the top of the 52-week range Euronext publishes, which now reads 7,671.74 to 9,671.11. Friday erased 128.90 points of it in a single session, a fall of 1.33 percent, and the index ended the day within three points of its own low. The record stands; the index simply spent Friday 1.33 percent below it. We took Friday's session apart line by line yesterday, including the full sixteen-name closing table.
The short version worth carrying into Monday is the breadth. On Thursday fifteen of the sixteen constituents rose and one fell. On Friday fifteen fell and one rose, and the one left standing was Mota-Engil, up three tenths of a percent. NOS went from the top of Thursday's board to the worst performer in the index, down 2.36 percent. The heaviest weights on the way down were BCP, off 2.24 percent to 1.176 euros, and Jerónimo Martins, off 2.22 percent to 17.66 euros, with Sonae close behind at 2.14 percent. Three of the four largest falls were consumer names, which is not the signature of a story about Portugal. It is the signature of a story about interest rates.
That story is the one this newsletter has been tracking all month: the European Central Bank raised rates a week ago, the Federal Reserve raised on Wednesday, the Bank of England held on Thursday and the Bank of Japan raised on Friday, taking its policy rate to the highest level since 1995. Three increases in eight days from three of the four largest central banks in the world is the kind of sequence that reprices every equity market at once, and it did.
Portugal Carries 3.90 Percent Into Monday, and France Spent Saturday Explaining Why It Pays 4.57
Portugal's ten-year yield closed the week at 3.90 percent, up five basis points on Friday, against a German Bund at 3.51 percent. That is a spread of 39 basis points, out from 37 on Thursday. Portugal borrows ten-year money 10 basis points inside Spain at 4.00 percent, 40 inside Greece at 4.30, 53 inside Italy at 4.43 and 67 inside France at 4.57. The United States ten-year sits at 5.01 percent. Those are TradingEconomics country-page levels stamped 18 September, and the gaps are recomputed here.
France is the number to watch, and France spent today explaining it. The Ministry of Economy and Finance in Paris told a press conference on Saturday that French public debt will reach 119.3 percent of gross domestic product in 2026 and 121.7 percent in 2027, both records, and the highest since 1995 on the national statistics institute's own series. "This rise is mechanical. It is the consequence of a deficit that remains high," the ministry said, having submitted its 2027 budget texts overnight to the High Council of Public Finances, the body attached to the French Court of Auditors whose opinion on the "sincerity and credibility" of the projections is compulsory.
The deficit path behind that debt number: 5.1 percent of GDP in 2025, a forecast 5.4 percent in 2026, and 5.0 percent in 2027. Roland Lescure, the French finance minister, called the 2027 target "ambitious" but "obviously achievable" on Thursday. The ministry added that the debt ratio can only stabilise once the deficit is down to 3 percent, an objective still pencilled in for 2029. Prime Minister Sébastien Lecornu set out a budget on Thursday built on 54 billion euros of effort, leaving parliament to decide the politically sensitive parts, including the measures touching pensioners. The state and social security budget bills go to the French Council of Ministers on 1 October.
Read that alongside the yield. France now pays more for ten-year money than Italy, its yield rose 12 basis points on Friday against Portugal's five, and on TradingEconomics' longer measures the French ten-year is up 1.02 points over twelve months against Portugal's 0.73. The useful thing for a Portuguese reader is what has not happened: none of this has leaked into the Portuguese spread, which spent the week in a 35 to 39 basis point band. Portugal's problem, for now, is the level of euro-area rates in general, not its own credit.
Friday's Euribor Landed This Morning, and the Two Fixings That Matter Went Opposite Ways
Euribor fixings publish a day in arrears on euribor-rates.eu, so Friday's numbers appeared this morning and are the freshest market data in this edition. They are also, unhelpfully, a split decision.
The twelve-month rate fixed at 3.343 percent on 18 September, down two tenths of a basis point from Thursday's 3.345. The six-month went the other way, up 1.6 basis points to 2.978 percent from 2.962. The three-month fell 1.3 basis points to 2.620 percent, the one-month eased two tenths to 2.473 percent, and the one-week rose three tenths to 2.357 percent.
Those two middle rates are the ones that set the payment on a Portuguese variable-rate mortgage, and after a week in which the twelve-month rose sharply on Monday and then drifted back, one of them ended the week up and the other flat. The week-on-week comparison is the honest one: the twelve-month fixed at 3.160 percent on 11 September, so it is 18.3 basis points higher than it was seven days ago. A borrower whose contract reprices off the twelve-month in the next few weeks will feel that, and two quiet days at the end of the week have not undone it.
On the currency, the European Central Bank's daily reference rate put the euro at 1.1460 dollars on Friday, down 0.18 percent on the day and down for a seventh consecutive publishing day, from 1.1652 on 9 September. That is a 1.65 percent fall across seven sessions and the longest unbroken run of declines anywhere in the ECB's published 90-day window. The next fixing is Monday afternoon.
Brent Settled at 103.87 Dollars, and Macron Wants a G7 on Opening the Strategic Reserves
Now that the week is closed, the oil number firms up. Brent for November delivery settled on Friday at 103.87 dollars a barrel on the Intercontinental Exchange in London, down 0.91 percent, or 95 cents from Thursday's 104.82. That is a lower close on the week, the first weekly fall in three, and it comes after the contract spent the middle of the week at four-month highs.
What pulled it down at the end is a political signal rather than a barrel. Emmanuel Macron told reporters on Friday that "we will have in the coming weeks a G7 dedicated to energy matters, to consider the options for a possible release of strategic reserves, as we did a few months ago." The precedent he is invoking is March, when International Energy Agency member countries released 400 million barrels to unblock the market after the American and Israeli strikes on Iran on 28 February.
The counterweight has not gone away. Houthi forces have stepped up attacks on Saudi energy infrastructure, and as we reported yesterday, Saudi Aramco has told at least two European refining customers that they will get no crude allocation at all next month. The G7 can release reserves. It cannot make a specific cargo arrive at a specific European refinery. For Portugal, which buys every barrel it burns, the distinction is the whole story, and it is why the pump price and the electricity price have gone on rising through a week when the benchmark fell. Our news desk covered the fuel-tax response this afternoon.
Some of that reached the street today. A few dozen people marched through Porto on Saturday afternoon, from Praça do Marquês, in a protest against fuel prices and the cost of living convened for 15:00 by a group of business owners. "We are a group of business owners feeling the brutal increase in fuel prices first hand," the movement's spokesman, Ricardo Pinto, told Lusa. The organisers asked people not to fill up today and to use public transport instead.
Montenegro Rings the New York Closing Bell on Tuesday, in a Year Portugal Sold the Americans 9.7 Billion Euros
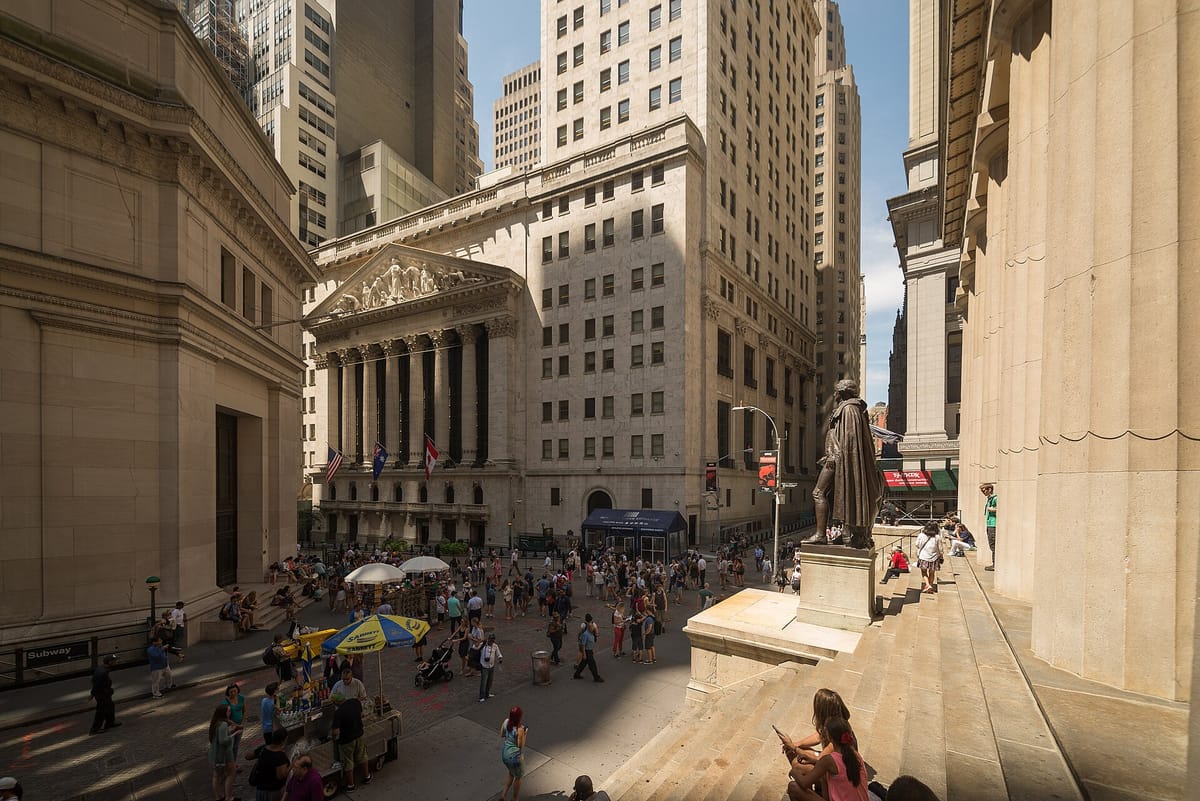
Luís Montenegro flies to New York this week for the 81st United Nations General Assembly, and his office has told Lusa that Tuesday, the first day of the trip, will be given over to the commercial relationship rather than the diplomatic one. The centrepiece is the closing bell ceremony at the New York Stock Exchange, where the prime minister will be the exchange's guest and will press the button that ends Tuesday's session.
The numbers his office is taking with him are worth setting out, because they are the argument. In 2025 the United States was Portugal's fourth largest customer for goods, taking 5.8 percent of national goods exports, worth 4.6 billion euros, and its tenth largest supplier, at 2.1 percent of imports and 2.4 billion euros. Widen it to goods and services together and the picture changes shape: total exports to the United States were 9.7 billion euros in 2025 against 3.6 billion of imports, a surplus of roughly 6 billion, and Portugal has run a positive balance with the Americans every year since 2021. Average annual growth over 2021 to 2025 was 15.4 percent on the export side and 5.0 percent on the import side. Travel and tourism, which made up 51.6 percent of national services exports in 2024, grew 8 percent in 2025. American direct investment into Portugal reached 4.8 billion euros in 2025, up 15.9 percent, making the United States the seventh largest investor in the country.
The prime minister's office says the invitation "recognises Portugal's economic and financial trajectory", citing growth above the euro area, a budget surplus, falling public debt, record employment and, explicitly, the recent Fitch upgrade of the Republic to A+. We covered that upgrade on 4 September, including the detail that it came straight out of the agency's model with no committee override.
Two Portuguese predecessors have done this. Durão Barroso rang the closing bell in 2007 as president of the European Commission, and Cavaco Silva rang the opening bell in 2008 on an official visit as President of the Republic. Also on Tuesday, Montenegro visits a Portuguese filigree shop on Times Square, which his office frames as a signal of support for the international expansion of Portuguese companies. That shop has a name, and we wrote about the company that runs it this morning: Joalharia do Carmo, a Lisbon jeweller founded in 1924, which committed six million euros to a ten-year lease on Times Square and is now opening in Paris.
The remaining two days go to the General Assembly, a few months before Portugal takes up its non-permanent seat on the United Nations Security Council in January, for the 2027 to 2028 term.
A Golegã Sauce Maker Buys Dona Sarah, and Has a Moroccan Factory on the Table
Casa Mendes Gonçalves, the Golegã company behind the Paladin, Moreno and Sacana brands, has bought Alimentos Guadiana, owner of the Dona Sarah brand, and the healthy-food brand Diese, and is now in contact with local partners about opening a production plant in Morocco. Carlos Mendes Gonçalves, the chief executive and owner, set out the plan to Dinheiro Vivo.
The Dona Sarah deal brings with it a second factory, at Moura in the Alentejo, and the price was not disclosed. "This is not the typical investment of a larger company acquiring another to absorb it, but acquiring it, in this case in full, to keep it and to develop it," Mendes Gonçalves said. Every job was kept, including that of the previous owner, who stays on as manager. The Diese acquisition was smaller, a 300,000 euro investment, and the logic there is explicitly a repeat of what the company did with Paladin 26 years ago: take an old Portuguese brand, in this case a pioneer in healthy food, and relaunch it. Three vinegars and four nut creams have already reached the shelves under the new Diese identity, with eight teas and infusions to follow.
The scale underneath this is larger than the brand names suggest. The Golegã plant produced 18,423 tonnes of sauces and condiments in 2025, plus 14,131 tonnes of vinegar, 1,657 tonnes of non-food vinegar and 448 tonnes of nut creams, after a ten million euro investment that lifted capacity by 30 percent. The company employs 420 people and turned over 63.5 million euros last year, up 6 percent, selling to Sonae, Pingo Doce, Auchan, Lidl, McDonald's and Kikkoman among others.
Exports are about 20 percent of sales across 29 markets, with Spain and Morocco the largest. Morocco is where the next factory would go, and the reasoning is logistical as much as commercial: it shortens the distance to Arab markets, where the company already holds halal certification, and it secures local raw material. "We are not in the position of a buyer imposing anything, so we want to find the ideal partner to make this journey together," Mendes Gonçalves said, conceding that the current geopolitical situation has made the push further east harder. The business plan runs to 2030 and targets 100 million euros of revenue, exports at 30 percent of sales and own brands at close to 40 percent.
Bleap Puts Brazil's Pix Inside a European IBAN, and Trade Republic Gives Its Old Clients Forty-Eight Hours
Bleap, a fintech founded in 2023 by two Portuguese former Revolut employees, João Alves and Guilherme Gomes, has processed 100 million euros of transactions so far this year, against 25 million across the whole of 2025. The product is a bank account built on blockchain rails that lets users spend stablecoins with a Mastercard, and the growth step the founders are betting on is remittances to Brazil.
In July the company obtained its licence under the European Union's Markets in Crypto-Assets Regulation, which is what made the remittance product possible. A Brazilian registering with Bleap supplies a CPF number, the Brazilian equivalent of a NIF, and receives a European IBAN with a Pix key attached to it that behaves exactly like a Pix key in Brazil. Reais sent from an account there arrive here in seconds, converted at the mid-market rate, with no fee and without the Brazilian tax on financial operations. The reverse leg, euros from Europe to a Brazilian account, is due before the end of September.
Why Brazil first is a straightforward market calculation. "We started looking for the market where the need would be greatest, where there would be an advantage for us, based in Europe: a market with a lot of migration coming here, and where the current players were charging a very high fee," Alves told Dinheiro Vivo. Colombia into Spain and Peru were considered; Brazil won on continuous inbound flow, and on the finding that in their interviews every single Brazilian was using one incumbent. Bank of Portugal data supports the sizing: Brazilians resident in Portugal send more money home than any other immigrant group, more than 341 million euros in 2025. The company raised six million dollars in January, over 5.2 million euros, in a round led by Blossom Capital, and is separately preparing a euro savings product paying 3.7 percent alongside an existing dollar product at around 7 percent.
A different kind of fintech story, and one that will land on some readers' phones: Trade Republic has begun withdrawing two benefits from Portuguese clients who declined to move their account to its new Portuguese branch. Interest on uninvested balances and 24-hour customer support now apply only to clients who migrate their IBAN, the company confirmed to ECO. Several clients who had not migrated received an email with a two-day deadline: "If you do not update your account in the next two days, you will stop receiving interest and will lose access to our 24h Customer Support."
That is a sharp change of tone. When the branch opened on 16 July, with a national IBAN, a free current account and a 3 percent rate for new clients on balances up to 50,000 euros, the company said existing clients would continue to receive the European Central Bank rate, then 2.25 percent, on their entire balance, with no mention of deadlines or lost services. Asked why the services were withdrawn, Trade Republic told ECO the differences "arise from operational and technical questions" and that running two account configurations in parallel "generates significant complexity and costs". It says migration remains optional and denies any portfolio conversion target.
There is a second detail in that story worth knowing whatever you decide. Uninvested balances at Trade Republic sit with partner banks, including Deutsche Bank, HSBC and Crédit Agricole, and are covered by the relevant national deposit guarantee schemes up to 100,000 euros per client per institution. Above a threshold the company calls the partner amount, fixed at 15,000 euros for clients in the Portuguese branch, the excess is no longer a bank deposit at all: it is placed in money market funds run by managers such as BlackRock and BNP Paribas, which the Fundo de Garantia de Depósitos (Deposit Guarantee Fund) does not cover. Trade Republic argues the segregation of those fund assets offers equivalent protection by a different route. Both statements can be true; they are not the same protection, and the difference matters above 15,000 euros.
Three More Deals: Fitness Park, an Aircraft Maintenance Firm, and Impresa's Programme Guides
Gyms. Providence Equity, the American private equity firm that owns VivaGym and absorbed Fitness Hut into it in Portugal, is among the best-placed bidders for the French chain Fitness Park, valued at around 600 million euros. The Spanish daily Expansión reports, in an account carried by ECO, that the sale is run by JPMorgan, that four potential buyers remain, and that the plan is to close by the end of the year. Fitness Park is owned by Philippe Herbette, with Future French Champions, a vehicle of the Qatar Investment Authority and Bpifrance, as principal minority shareholder; it runs more than 400 sites and turns over more than 400 million euros a year including franchises. Six of those sites are in Portugal, spread across Porto, Guimarães, Carnaxide, Braga and Aveiro, and Providence's intention is to keep both brands, so they would not have to change their signs.
Aircraft maintenance. LAS Maintenance, the Portuguese company founded by João Louro, has passed a majority stake to Nayak Aircraft Services, a European group that already had a small Portuguese operation and wanted a larger share of the market. Jornal Económico reports that CMS Portugal advised the buyer, with a team led by corporate and mergers partner Tiago Valente de Oliveira, and Sfera Legal advised the Portuguese side, led by Nuno de Abranches Namora, with the consultancy Wise Rocket also on the seller's side. "Nayak already had an operation in Portugal, but it was a small operation. They wanted to increase their market share, and that is what brought them to a significant operator like LAS," Abranches Namora told the paper. The value was not disclosed.
Television metadata. InfoPortugal, part of the Impresa group, has sold its electronic programme guide and content discovery business to Media Press Group, a European metadata company, for an undisclosed sum. The business will be run by a new Portuguese entity licensing the InfoPortugal name; ownership of the brand stays with Impresa, as does the rest of InfoPortugal's geographic information systems work. "With this acquisition, Media Press Group becomes the number one provider of TV metadata and EPG services in Portugal," said Magdalena Cechnicka, the buyer's chief executive. The unit generated 2.6 million euros of revenue in 2025, up 62.9 percent on the year, and 1.3 million in the first half of 2026. It is a small transaction by the standards of this section, and it is the kind that tells you where a listed media group thinks its margin is.
German Investors Are Watching Sines, and the Complaint Is the One You Would Guess
Markus Kemper, president of the Câmara de Comércio e Indústria Luso-Alemã (Portuguese-German Chamber of Commerce and Industry), told ECO in an interview published today that German companies are paying close attention to the artificial intelligence gigafactory Portugal is bidding to site at Sines, and are worried about the bureaucracy around it.
"There are always huge investments in the pipeline, because Portugal is quite fashionable," Kemper said, adding that "investments like the AI gigafactory will attract a lot of German investors", because the Iberian Peninsula is more attractive than the competition. His argument, as ECO summarises it, is that the absolute shortage of AI processing capacity in Europe works in Portugal's favour, because energy here costs less than elsewhere. The rest of the interview sits behind ECO's paywall, so the bureaucracy complaint in the headline is as far as we can follow it first hand.
The context readers will want: Portugal earmarked 200 million euros over seven years to anchor the Iberian bid, and the decision on where the European gigafactories go is not Lisbon's to make. What Kemper is describing is the part Lisbon does control, which is how long it takes to get a permit.
Knight Frank Puts Comporta on Europe's Luxury Map, and a London Lawyer Builds Eleven Villas Above Faro
Two property items that are really one item. Knight Frank published The Residence Report on Friday, and it puts Comporta and the Algarve at the centre of a structural shift in luxury residential investment towards branded residences and lifestyle destinations. The report calls Comporta "one of the most coveted coastal destinations in Europe" and identifies scarcity of supply, constrained by environmental regulation, as a principal driver of values there, with a thin pipeline of new projects. The example it picks out is Six Senses, developing a 70-unit hotel and 58 branded residences priced from 2.8 million euros, for delivery at the end of 2028.
The wider numbers explain why Portugal keeps appearing in these reports. Branded residence projects went from 354 in 2015 to 903 at the end of 2025, should pass 1,000 this year, and are projected to approach 1,800 projects and more than 300,000 units by 2031. In 2016 fewer than four in ten were outside major urban centres; today more than half are in non-urban markets, and Knight Frank expects 57 percent by 2028, with over half of new openings in coastal, island, mountain or resort locations. The report identifies Spain and Portugal as destinations attracting American families looking for asset protection and insulation from geopolitical risk, and not only for tax reasons. "The market has tripled in size over the last decade and we expect it to double again in the next five years," said Liam Bailey, the firm's global head of research.
The individual case arrived the same weekend. Neel Sachdev, global vice-chair of the law firm Paul Weiss and head of its London office, is investing in a development of eleven luxury villas at Santa Bárbara de Nexe, in the hills behind Faro, according to the Financial Times in an account relayed by ECO. The land, formerly an orange orchard, cost 1.5 million euros. One house is finished and the other ten are at various stages, with completion expected by 2028; each has a pool and each was valued this year at more than three million euros. The project is a partnership with a property investor Sachdev met when both lived in Hackney, in east London, and the builders, architects and interior designers are Portuguese. Sachdev, a private equity specialist who moved from Kirkland & Ellis to Paul Weiss in 2023 and grew its London office from around 15 lawyers to 275, thinks the Algarve can become "the California of Europe". Knight Frank, quoted by the same paper, notes that the supply of detached villas in the Algarve is still below demand, particularly in peripheral areas with room to appreciate.
Also: BCP's Buyback Passes 232 Million, AICEP Changes Hands on 1 October, and Açoreana Disappears After 134 Years
BCP. Banco Comercial Português has told the Comissão do Mercado de Valores Mobiliários (Securities Market Commission) that it has now bought more than 214 million of its own shares, for roughly 232.6 million euros, taking its holding to 1.45 percent of share capital. The programme was approved in May with a ceiling of 407 million euros, began on 4 June and is scheduled to run to 4 December, though the bank reserves the right to stop earlier if the board decides or if the capital and share limits are reached first. Just over 57 percent of the authorised amount has been spent with about eleven weeks to run, arithmetic done here. The share closed Friday at 1.176 euros after a 2.24 percent fall, having touched an eleven-year high earlier in the week.
AICEP. Ana Casaca takes over as president of the Agência para o Investimento e Comércio Externo de Portugal (Trade and Investment Agency) on 1 October, under a Council of Ministers resolution published in the Diário da República on Friday, which also authorises her to combine the post with university teaching and with her seat on the European Innovation Council Board. She has been Galp's global innovation director since 2020. She succeeds Madalena Oliveira e Silva, who is retiring, and becomes the third person appointed to run the agency under Luís Montenegro's governments in a little over two years. An energy company's innovation chief moving to run the body that courts foreign investment is a reasonable signal of where the agency thinks the next mandate's deals are.
Açoreana. Generali Tranquilidade announced on Friday that the Açoreana Seguros brand will disappear after 134 years and be absorbed into Generali Tranquilidade, with a multimedia campaign running across the Azores until the end of October under the line "Açoreana Seguros is now Generali Tranquilidade". Açoreana was founded in Ponta Delgada in 1892, nationalised in 1975 and later privatised through the Banif group; it keeps 11 shops and around 80 agents and brokers in the archipelago. The insurer stresses that this is a branding change only, with no alteration to contract terms, cover, premiums or policyholder rights, and that Generali Seguros remains the underwriting entity. Generali is now down to two brands in Portugal: LOGO for direct sales and Generali Tranquilidade for everything else.
Monday
Lisbon reopens at 08:00 with a record 129 points above it and a 39 basis point spread behind it. The immediate question is whether Friday's fall was the whole adjustment to three central bank moves in eight days or the first instalment; the answer will show up in BCP and the three consumer names that did the damage, not in the index level. Diesel and petrol both rise at the pumps, by roughly 6.5 and 5 cents a litre, with the extra cent of tax relief announced on Friday already netted off. Watch France, where the debt projections published on a Saturday go to the High Council of Public Finances before the budget bills reach the Council of Ministers on 1 October, and where a 4.57 percent ten-year is now the euro area's problem child. And watch the clock on Tuesday evening in Lisbon, which will be a little after four in the afternoon on Wall Street.