The Constitutional Court Rules That the Method Used to Value Wind Farms for Property Tax Breaches the Constitution, and Dams, Golf Courses and Campsites Sit on the Same List
The Constitutional Court says the rule used to value wind farms for IMI breaches the Constitution: Parliament never defined which properties use the cost method, or how it works. The ruling binds one case for now.
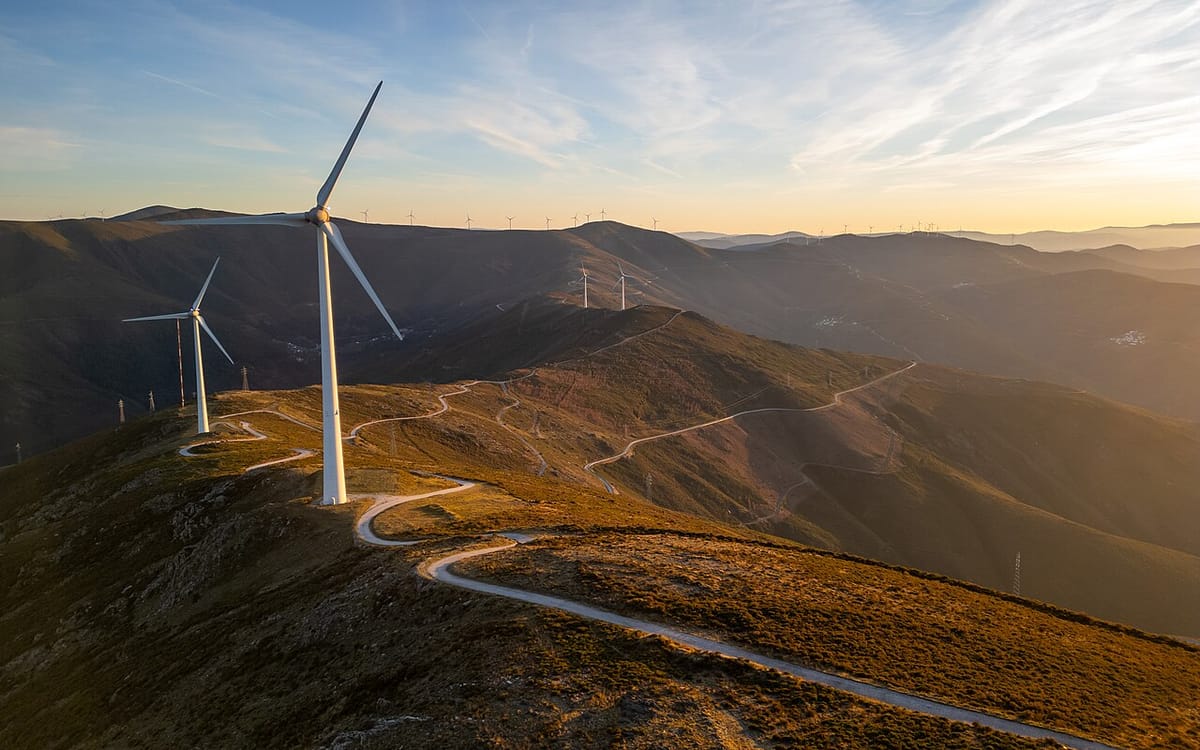
The Tribunal Constitucional (Constitutional Court) has ruled that the rule the Tax Authority uses to value wind farms for the Imposto Municipal sobre Imóveis (IMI, the municipal property tax) is unconstitutional, because Parliament never wrote into law either which properties the method applies to or how the method actually works. The decision, Acórdão n.º 777/2026, was signed on 24 September by the court's Third Section.
It is a concrete review: it settles one dispute over one wind-farm property and does not strike the rule from the statute book. But the reasoning reaches well beyond wind power, because the same valuation route is prescribed for a long list of other installations, from dams to golf courses and campsites.
The case: one property in a wind park near Amarante
The dispute began when a company, anonymised in the ruling as "A., S.A.", challenged a second valuation by the Autoridade Tributária e Aduaneira (AT, the Tax and Customs Authority). The valuation put a taxable property value of 285,440 euros on an urban property registered in the parish of Ansiães, which belongs to the Portal da Freita wind park.
On 31 December 2025 the Tribunal Administrativo e Fiscal de Penafiel (Penafiel Administrative and Tax Court) upheld the company's challenge and refused to apply the valuation rule, calling it incompatible with the constitutional principle of tax legality. The Ministério Público (Public Prosecutor's Office) appealed, as it must when a court refuses to apply a rule on constitutional grounds, and defended the rule. The court dismissed that appeal, so the Penafiel decision stands.
The rule that was judged
The rule comes from three pieces read together. Article 38 of the IMI Code sets out the standard formula for valuing urban buildings. Since the 2016 State Budget, its paragraph 3 says that commercial, industrial or service properties for which that formula "proves inadequate" are valued under Article 46(2), and paragraph 4 leaves it to a Finance Ministry order (portaria) to define which types of property those are.
Article 46(2) tells the assessor to use the "método do custo adicionado do valor do terreno", a cost method that adds the cost of the construction to the value of the land. Portaria n.º 11/2017, of 9 January 2017, then lists the property types that must be valued this way. The first entry is "Centros eletroprodutores" (power-generating plants). That is how wind parks end up on the cost method.
Two reasons the court gave
- Parliament handed a tax decision to the Government. The Constitution reserves the creation of taxes and the tax system to the Assembleia da República (Parliament). The court found that the word "inadequate" gives no real criterion: the law does not say when the standard formula should count as inadequate or on what basis. In practice, the court said, it is the administration, through the portaria, that decides which properties change method, and the listing of power plants therefore "assumes an innovative character" (our translation).
- The law names the method but never defines it. The Constitution also requires the law itself to set the essential elements of a tax, including its base. For the standard formula, the IMI Code spells out every factor. For the cost method, the court noted, neither the Code nor the portaria sets out a formula, its elements or the criteria for weighing them. "The law names the applicable method, but does not contain the normative criteria" that shape how it is applied, the judges wrote (our translation). Since IMI is charged on the taxable value, that gap goes to the heart of the tax.
The Public Prosecutor's Office had argued that the portaria only adds technical detail, that only towers and foundations are valued (not blades or rotors), and that the Supremo Tribunal Administrativo (Supreme Administrative Court) has repeatedly upheld wind-farm valuations under it. The court answered that what counts as a "property" is a question of ordinary law, not the issue here, and that the Supreme Administrative Court had looked only at whether the portaria stayed within its legal mandate, not at whether the mandate itself was constitutional.
The ruling leans heavily on Acórdão n.º 366/2026 of 21 April, in which the court struck down, also in a single case, the way the non-habitual resident (NHR) tax regime left it to a portaria to define the "high value-added" activities that qualify for its special rate.
What the ruling does not do
In a concrete review the judgment binds only the case in which it is given. Wind farms elsewhere are still valued under the same rule, and no IMI bill is cancelled automatically. The ruling also does not deal with the AT's Circular n.º 4/2026, which, as we reported in August, treats a wind or solar park as a single unit for valuation; the circular is not mentioned.
The Constitution (Article 281(3)) does provide a route to a general ruling: once the court has found a rule unconstitutional in three concrete cases, it can declare it unconstitutional with general binding force.
Dams, golf courses and campsites on the same list
The judgment covers only the rule as applied to wind parks. But the second reason, that Article 46(2) names a method without defining it, is not specific to wind. The portaria's annex, as published in 2017, also sends dams, electricity substations, gas and water installations, waste plants, telecoms towers, stadiums, swimming pools, theme parks, golf courses, fuel stations, campsites and car washes, among others, to the same method.
Jornal de Negócios, which first reported the ruling, said IMI and IMT (property transfer tax) assessments on those properties are also at risk.
Why it matters
IMI is municipal revenue. The councils that host these plants agreed in September on a formula for splitting that revenue and have been pressing for more of it. A rule that can be challenged property by property puts part of that income in doubt until Parliament writes the method into law.