The 2027 Budget Would Extend IMI and IMT Breaks on Restored Old Buildings to 2031, Along With Tax Relief for Common Land
Article 138 of the budget bill prolongs the IMI and IMT exemptions for rehabilitated buildings, in urban rehabilitation areas or over 30 years old, and the tax break for common land, to the end of 2031. What owners get, what Mais Habitação already removed, and the vote dates.
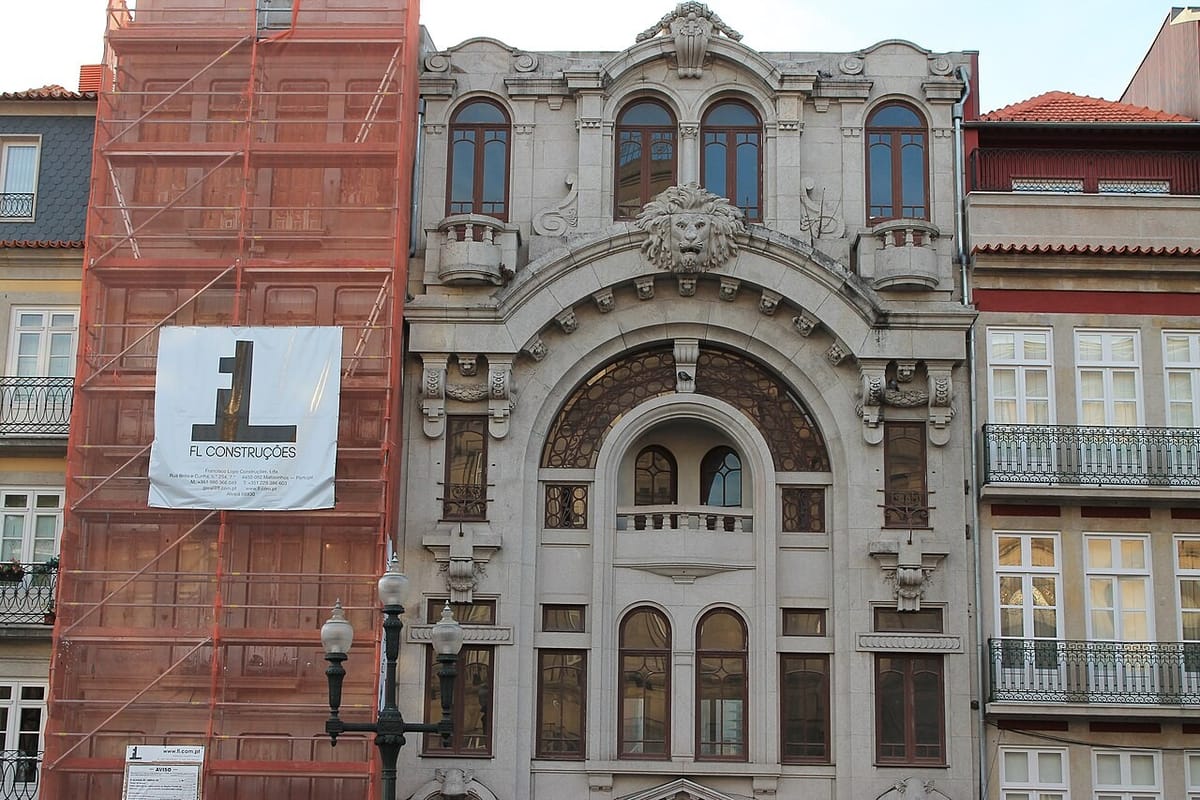
Owners who restore old buildings would keep their exemptions from IMI (the annual municipal property tax) and IMT (the property transfer tax) until the end of 2031 under the 2027 State Budget bill. The same clause keeps an income tax exemption for baldios, the common land held by rural communities.
The extension is in article 138 of Proposta de Lei n.º 110/XVII/2.ª, the budget bill delivered to parliament on 8 October. It prolongs articles 45, 58, 59 and 61 to 66 of the Estatuto dos Benefícios Fiscais (EBF, the Tax Benefits Statute) to 31 December 2031. Jornal de Negócios, which first reported the measure, describes it as a five-year renewal.
What the rehabilitation breaks give
Article 45 covers buildings or flats finished more than 30 years ago or located in an área de reabilitação urbana (ARU, an urban rehabilitation area marked out by the council). The works must follow the urban rehabilitation rules, lift the conservation rating by two levels to at least "good", and meet energy efficiency requirements. The law then gives:
- no IMI for three years from the year the works finish, renewable for five more if the property is let as a permanent home or is the owner's permanent home (the renewal needs a municipal assembly vote);
- no IMT on a purchase for rehabilitation, if the buyer starts work within three years;
- no IMT on the first sale after the works, if the buyer lets it as a permanent home or, inside an ARU, lives in it;
- half the usual fee for the conservation assessment.
The council must recognise the works; the request goes in with the planning application. Since 2022, the IMT exemption on that first sale is lost if the home changes use within six years, is not lived in within six months or is not let within a year, and the buyer must ask the Tax Authority to charge the tax within 30 days. Foreign residents who own or buy in Portugal are covered on the same terms.
What has already gone
Older guides to "ARU benefits" promise more than the law now gives. The Mais Habitação housing law (Lei n.º 56/2023) repealed most of EBF article 71, including the 5 percent rates on rental income and capital gains from rehabilitated property. What survives there is an IRS deduction of 30 percent of certified rehabilitation costs, capped at 500 euros. Rehabilitation building contracts inside an ARU still carry 6 percent VAT under item 2.23 of the VAT Code's reduced-rate list. Neither appears in the budget's extension clause.
Common land and the rest of the clause
Under article 59, baldios pay no IRC (corporate income tax) on income from the land, including leases, if it is reinvested in forestry, the land or the community within four years; baldio land registered in the community's name is also free of IMI. The 2026 budget had extended this article only to 31 December 2026.
The clause also carries article 58, which counts only half of authors' copyright income for IRS, and the articles on relief for donations. Under EBF article 3, a benefit already acquired while a rule is in force is kept even if the rule later lapses.
What parliament still has to do
Nothing is law yet. Parliament's calendar sets the first vote on the bill for 28 October; amendments are debated from 29 October and the final vote is on 24 November. The bill's household measures are in our report on what the 2027 budget changes for households, and landlords may want to read about the Tax Authority's letters to 33,381 landlords.