Overcharged 23 Percent VAT on Renovation Work in an Urban Rehabilitation Area? Your Builder's Credit Note and a Four-Year Limit Decide Whether You Get the Difference Back
A law backdated to 2009 means works in urban rehabilitation areas needed no approved operation plan to get 6 percent VAT. Builders can refund the extra 17 points by credit note, but only within four years and if the area had not lapsed.
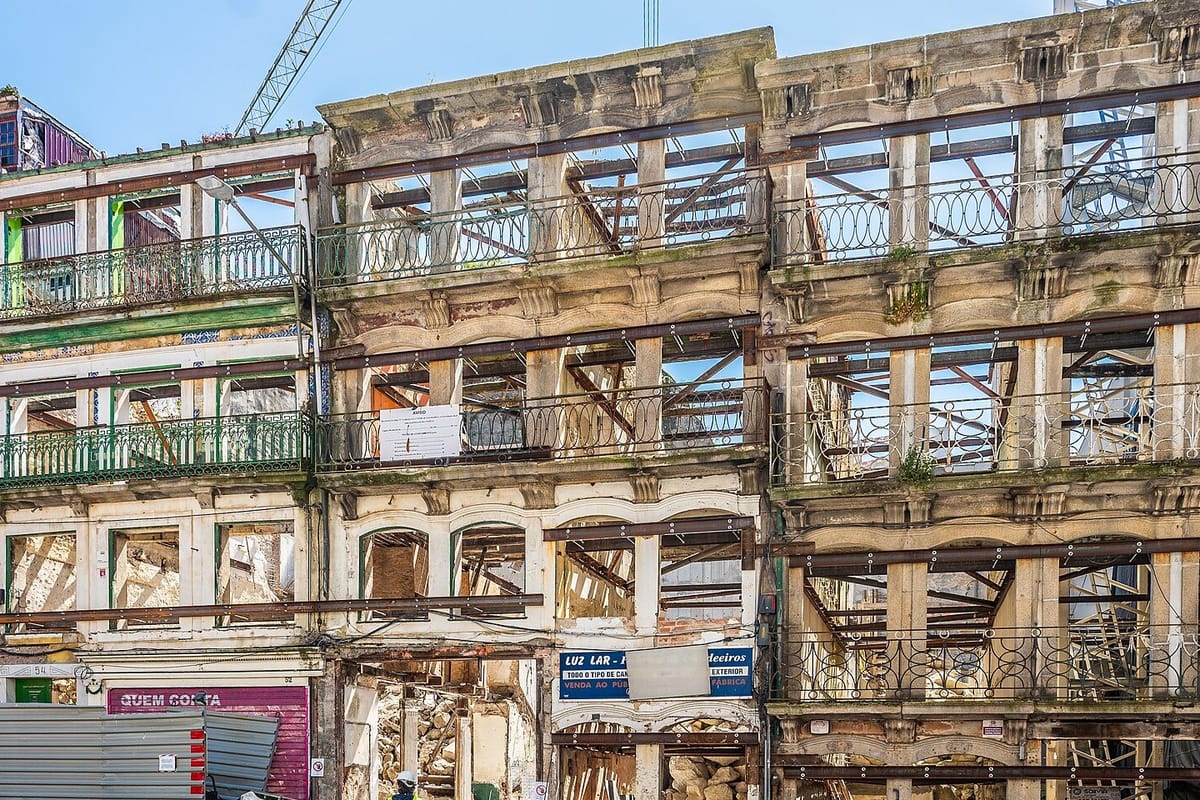
Homeowners and developers who paid 23 percent VAT, not 6 percent, on building work in an urban rehabilitation area can now seek the difference back. The opening comes from Lei n.º 48/2026 (Law 48/2026), published on 17 August, and from instructions the Autoridade Tributária e Aduaneira (AT, the tax authority) sent to its offices in Ofício-Circulado n.º 25121/2026 (Circular 25121/2026), dated 25 September. Advisers quoted by Observador on 16 October see real limits.
What the law settled
From 2009 to 6 October 2023, item 2.23 of List I of the Código do IVA (VAT Code) gave the reduced rate to "urban rehabilitation" contracts on buildings in an área de reabilitação urbana (ARU, urban rehabilitation area). The AT read this as also requiring an operação de reabilitação urbana (ORU, urban rehabilitation operation) approved by the council, and taxed many jobs at the normal rate. The Supremo Tribunal Administrativo (Supreme Administrative Court) backed that reading in a ruling of 26 March 2025.
Law 48/2026 says otherwise: works in a legally delimited ARU qualify "regardless of the approval" of an ORU. It takes effect back to 1 January 2009. The old wording also still covers projects whose licence, prior communication or prior information request reached the council before 7 October 2023.
The conditions
- The ARU must still have been valid. The AT's circular points to the urban rehabilitation regime, under which an ARU approved without an ORU lapses after three years. The 6 percent rate applies only if, on the date the VAT became due, the ARU had an approved ORU or had been delimited less than three years earlier.
- Old deadlines stay closed. The circular says the backdating does not reopen time limits that have already run out. Where a supplier overcharged because the rate was wrong in law, the correction must fall within four years.
- It must be a building contract (an empreitada) on a property in the ARU.
Advisers told Observador this leaves, in practice, works invoiced from 2022 to October 2023, and that many disputed assessments are already closed. One lawyer said Vila Nova de Gaia, which had no approved ORU until October 2025, and Braga have the most cases.
What a homeowner has to do
Where the AT played no part, the circular says the correction is a matter between the builder and the customer; it sets out no route for a private client to claim the money from the tax office. The builder issues a credit note for the excess, the gap between 23 and 6 percent (17 euros on every 100 euros of work before VAT, at mainland rates). The builder can recover that VAT from the State only once it holds proof that the client was refunded.
Before you ask, check your invoice dates, when the project was filed with the council, and whether the council's ARU covered your street at the time.
Where the AT itself raised the VAT, the circular tells its offices to drop pending corrections that rest only on the missing ORU. It also accepts requests for an official review (revisão oficiosa) of such assessments, though they are not granted automatically.
What applies to renovations today
Law 48/2026 does not change the current rules. Since 7 October 2023, item 2.23 covers rehabilitation of buildings in an ARU. Separately, item 2.27 gives 6 percent on renovation and repair of homes anywhere in the country, but on labour only, unless materials make up no more than 20 percent of the job. Ask your builder which item your invoice cites. Owners of restored buildings may also qualify for property tax breaks, which the 2027 budget would extend to 2031.