The Government Writes the NHR Regime's List of 20 Percent Tax Jobs Into a Bill, After the Constitutional Court Faulted a Ministerial Order
A bill approved on 8 October puts the high value-added activities behind NHR's 20 percent IRS rate into law, without widening them, for people still under the transitional rules. Its text is not yet public. What the April ruling said, and what NHR holders should know.
The list of jobs that qualify for the NHR regime's 20 percent flat rate is to be written into law, less than six months after the Constitutional Court found, in one taxpayer's case, that leaving it to a ministerial order breached the Constitution. The Conselho de Ministros (Council of Ministers) approved a bill on Thursday, 8 October, that sets out these "high value-added activities" in law form without widening them. It covers only people who already had NHR (Residente Não Habitual, non-habitual resident) status and who remain under the transitional rules.
What the government said
The Council of Ministers communiqué gives the measure a single sentence. It says the proposta de lei (government bill) puts into law form, "and without widening the scope", the high value-added activities relevant to taxpayers who already benefited from the non-habitual resident regime and who are still covered by the transitional rules now in force. The stated aim is to reinforce the regime's constitutional compliance and protect legal certainty.
The communiqué, issued from the same meeting that approved the 2027 State Budget bill, does not name the court ruling, give a bill number or timetable, or say whether the law would reach past tax years. The text has not been published. By Sunday night the bill did not yet appear on the Assembleia da República (Parliament) list of newly submitted initiatives.
What the Constitutional Court decided
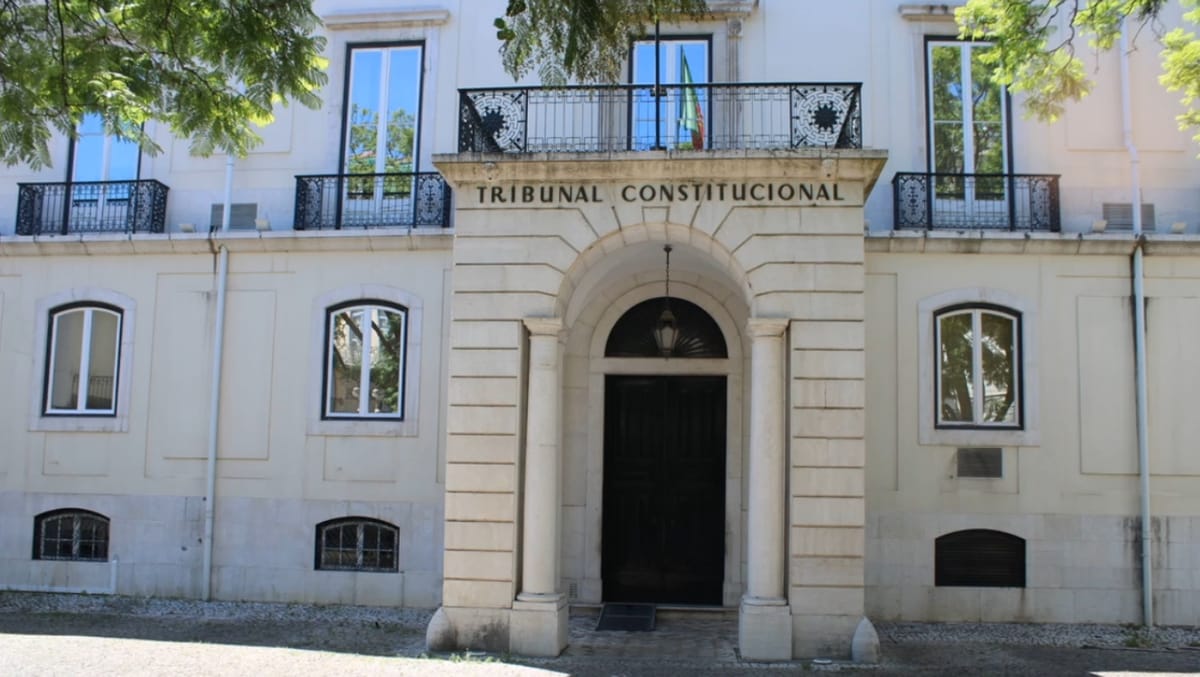
In Acórdão n.º 366/2026 (Ruling 366/2026), dated 21 April 2026, the first section of the Tribunal Constitucional (Constitutional Court) looked at the two rules behind the 20 percent rate. Article 72(10) of the IRS Code, in the wording of Lei n.º 3/2019, taxed NHR holders at 20 percent on work and self-employed income from high value-added activities of a scientific, artistic or technical nature, "to be defined" by an order of the finance minister. That order is Portaria n.º 12/2010, as amended by Portaria n.º 230/2019.
The Court held both rules partly unconstitutional. Article 72(10) failed insofar as it handed the primary definition of the activities to an administrative regulation, for self-employed (category B) income. Article 103(2) of the Constitution says taxes are created by law, which sets their incidence, rate, tax benefits and taxpayers' guarantees. Article 112(5) bars a law from giving any other kind of act the power to interpret, supplement, change, suspend or revoke its provisions. The order failed where it listed "directors of administrative and commercial services" as a high value-added activity, under articles 103(2) and 165(1)(i), the second of which reserves the creation of taxes and the tax system to parliament.
The case came from tax arbitration at the CAAD (Centro de Arbitragem Administrativa, Administrative Arbitration Centre), case 732/2024-T. A taxpayer challenged his 2022 IRS assessment, arguing that his professional income from work in Cyprus should have been taxed at the NHR rate of 20 percent because his activity fell under the directors' heading. On 27 January 2025 the arbitral tribunal refused to apply the two rules and rejected his claim. The Ministério Público (Public Prosecutor's Office) was required to appeal, though it agreed the rules were unconstitutional; the taxpayer defended them. The Court dismissed the appeal, so the decision rejecting his claim stands.
A ruling in one case does not remove a rule for everyone. Under article 281(3) of the Constitution, the Court can declare a rule unconstitutional with general binding force once it has judged it unconstitutional in three concrete cases.
What NHR is, and who is still on it
NHR was created by Decreto-Lei n.º 249/2009, which gave the status for a period of 10 consecutive years. Since 2020 the list of qualifying jobs has been built on codes of the Classificação Portuguesa de Profissões (Portuguese Classification of Occupations). It includes company directors, doctors, engineers, university lecturers, IT specialists and skilled trades, and requires at least level 4 of the European Qualifications Framework or five years of proven professional experience.
The 2024 State Budget law, Lei n.º 82/2023, revoked article 72(10) and added a new incentive for scientific research and innovation (IFICI). Its article 236 keeps the old NHR rules running, until the end of the 10-year period counted from when a person became resident, for people already registered, people who met the residence conditions by 31 December 2023, and people who became resident by the end of 2024 holding certain documents dated before set cut-offs, such as a work contract or a lease.
Take-up of IFICI has been small: 946 people, according to the Tribunal de Contas (Court of Auditors) figures in our report on 29 September.
What happens next
A government bill needs a vote in parliament before it becomes law. Until the text is published, it is not known exactly which activities the bill lists, whether it reaches back to earlier tax years, or how it treats assessments and arbitration cases already under way.
What this means for you
- Nothing changes yet. The bill is not law and its text is not public. Your NHR status and the transitional rules are unchanged.
- The list is not being widened. The government says the bill adds no activities. If your job is not on the current list, this bill, as described, will not put it there.
- Know your occupation code. The 20 percent rate depends on which code of the Portuguese Classification of Occupations your work fits. The ruling dealt with the code for directors of administrative and commercial services, for self-employed income.
- Keep your evidence. Hold on to contracts, proof of qualifications or five years' experience, and your NHR registration.
- Disputes need the final text. If you are challenging an assessment, only the published bill will show how pending cases are treated.
For newcomers, NHR is closed and IFICI is the route; our NHR and IFICI guide explains both. The next step is the bill's arrival in parliament, where its text will show whether existing NHR holders' 20 percent rate rests on firmer ground.