Caixa Geral de Depósitos Secures Another 95 Million Euros of the Youth Home-Loan Guarantee, Leaving Little of the 2.3 Billion Euro Ceiling Unallocated, Público Reports
A Treasury order published on 20 October tops up the state bank's share of the guarantee that lets under-35s borrow the full price of a first home. Público says less than 70 million euros of the 2,300 million ceiling is left to allocate.
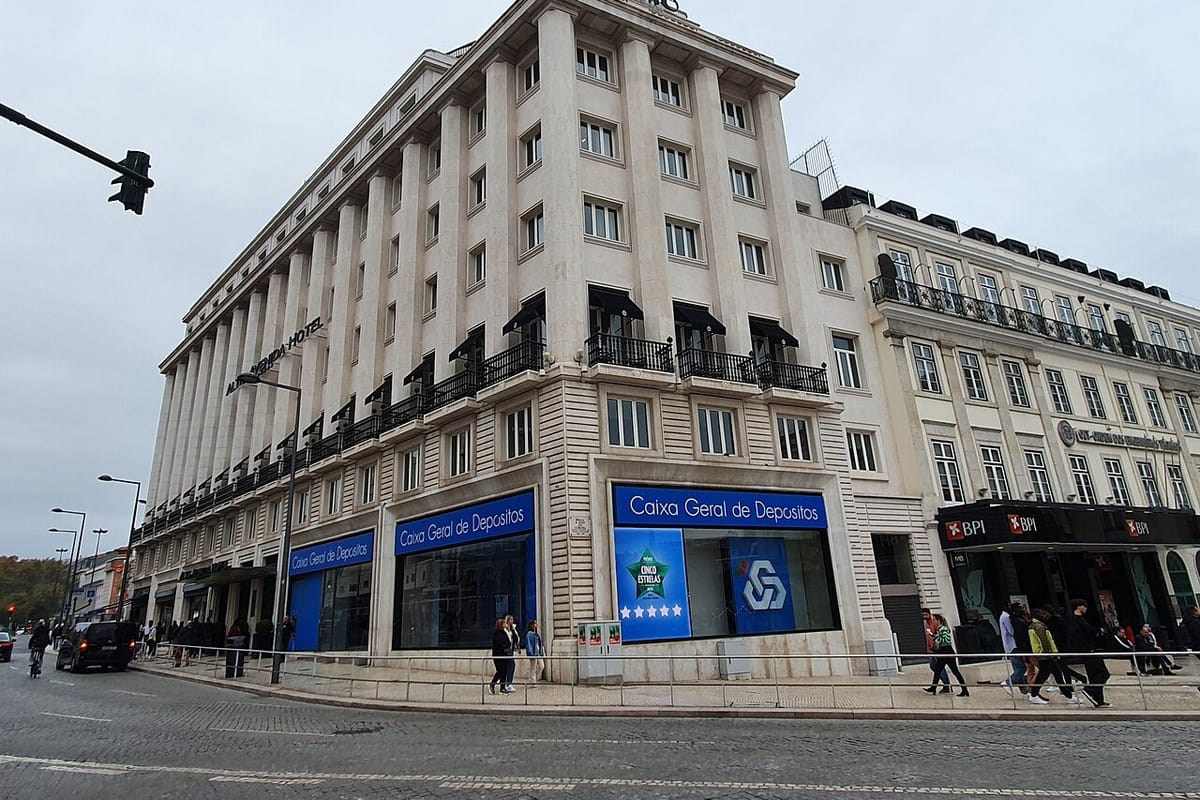
Caixa Geral de Depósitos, the state-owned bank, has been given another 95 million euros of the public guarantee that lets people aged 35 and under borrow the full price of a first home. The Despacho n.º 12739/2026 (a Treasury order), published in the Diário da República (the official gazette) on 20 October, says the top-up is needed so that "the participating institution that has exhausted its guarantee limit" can keep offering the scheme.
The order also sets out the national ceiling. The state first set aside 1,200 million euros in November 2024, then added 350 million in September 2025 and 750 million in April 2026, for a total of 2,300 million euros. Each bank gets its own share.
According to Público, which reported the order on 20 October, the new money brings Caixa's share to 602.4 million euros, the largest of any bank, and leaves less than 70 million euros of the 2,300 million unallocated. The paper adds that the government has not said whether it will raise the ceiling.
How the shares work
Under Portaria n.º 236-A/2024/1 (the ministerial order that regulates the scheme), the Finance Minister fixes the national ceiling and divides it among the banks that have signed up. A bank that expects to run out can ask the Entidade do Tesouro e Finanças (the state's treasury and finance agency, which handled Caixa's request) for more. The request form requires the bank to show that live guarantees already exceed 90 percent of its share. Each top-up needs a new order from the Finance Ministry. A September order, which Dinheiro Vivo reported gave Novo Banco and Banco Montepio 100 million euros between them, worked the same way.
Two practical points follow. A bank that has used up its share has no guarantee to offer until it is topped up, so shop around. And if you later move a guaranteed loan to another bank, the guarantee only travels with it if the new bank has signed up and has room in its own share.
Who qualifies
Decreto-Lei n.º 44/2024 (the decree-law that created the guarantee) and the regulation set these conditions for every buyer on the loan:
- aged 18 to 35, with tax residence (domicílio fiscal) in Portugal;
- income no higher than the eighth IRS (income tax) bracket, whose upper limit in Article 68 of the IRS Code is now 86,634 euros of taxable income;
- owning no urban residential property, and never having used the guarantee before;
- buying a first permanent home with a transaction value of no more than 450,000 euros;
- no outstanding debts to the tax authority or Social Security.
Nationality is not a condition. The law asks for tax residence, and the regulation's document list accepts "an equivalent document" in place of the Portuguese citizen card for non-nationals. The guarantee covers up to 15 percent of the transaction value (the price or, if lower, the valuation), lasts at most ten years, and the state charges no guarantee fee. The Banco de Portugal's (the central bank's) customer portal points out that banks are not obliged to lend, even to eligible buyers. If you default, the state repays the bank up to the guaranteed amount, and you then owe that sum to the state. Loans must be signed by 31 December 2026, although the regulation allows that deadline to be extended.
Banco de Portugal data count 40,148 guaranteed home loans worth 8,285.5 million euros from January 2025 to June 2026, 45.2 percent of all permanent-home loans taken out by under-35s. Young buyers can also claim the IMT and stamp duty exemption, and our mortgage guide covers the rest of the approval process.